Real Estate News & Information August 13, 2026

Local Market Update – August 2026

July brought a shift across our four markets: after a year of building inventory and softening prices, every market area moved into balanced territory, with prices staying relatively steady across the board. Buyers, working with more leverage than in recent years, are finding more homes to choose from and taking more time to make decisions. Sellers are seeing that homes priced right and presented well are still attracting buyers. It’s a market that rewards preparation on both sides of the transaction, and one where good strategy pays off.

KING COUNTY

With 3.1 months of inventory, King County settled comfortably into a balanced market in July. The median residential sold price came in at $995,000, down 1% year over year but up slightly from June, a sign that pricing may be leveling out. Active listings rose 25% from a year ago, giving buyers considerably more to choose from, while closed and pending sales dropped 10% and 11% respectively, showing that buyers are willing to wait. Well-positioned homes are still moving quickly, though: nearly a quarter sold above asking price. More than a third of homes (35%) sold only after a price change, a signal to sellers that strategic pricing from the start remains the clearest path to success. In the condo segment, the median price dipped 2% year over year to $519,975, while active listings grew 21%.

SEATTLE

Seattle offered a bit of something for both buyers and sellers in July. Buyers continued to see more options than last year, with a 16% year-over-year increase in active listings. For sellers, the market remained competitive: 31% of homes sold above asking price and over 80% went under contract within 30 days, the fastest pace among our four areas, proof that strong demand for the right homes is still out there. But even so, activity was down compared to last year: closed sales cooled 14% and pending sales fell 17% as buyers continued to wait and watch. The median residential sold price dropped slightly, down 1% month over month and 1% from last year to $999,500. In the condo market, the median price fell 5% year over year to $525,000 as active listings rose 12%.

EASTSIDE

The Eastside gave buyers the most room to maneuver of our four markets this July, with active listings up 38% year over year and available supply reaching 4.0 months, teetering on the cusp of a buyer’s market. That expanded selection translated to real negotiating power for buyers: nearly three-quarters of homes sold below asking or after a price change. The median residential sold price held essentially flat from last year at $1,575,000, and 74% of homes sold within 30 days. Eastside condos saw the median price drop just 1% even as active listings rose 28%.

SNOHOMISH COUNTY

Snohomish County was the standout market in July. Closed sales rose 3% year over year, the only market to post a gain across our four regions, even as active listings climbed 33%, giving buyers more choice without cooling transactions. The median residential sold price fell 6% year over year to $757,250, opening opportunities for more buyers. 40% of homes sold only after a price reduction, but 71% went under contract within 30 days, showing that buyers remain engaged and ready to act when the price is right. The condo market followed a similar trend, with closed sales up 9% even as the median price fell 6% to $500,000.

As we enter the final month of summer, the question on everyone’s mind is whether this new balance holds. Mortgage rates remain persistently high, and affordability concerns are keeping potential buyers on the sidelines. But for buyers who are ready, greater selection and softer prices than in recent years means more opportunity. Sellers who list in the coming months may find more interest, too, since fewer new listings typically hit the market after the summer season, and well-prepared homes could stand out even more as choices thin out. Whichever side of the of the transaction you’re on, an experienced Windermere advisor can help you map out a plan and timeline that fits your goals.

Read more.

Sellers August 11, 2026

When Is a Home Seller Paid? Understanding the Closing Process

A successful home sale doesn’t end with an accepted offer. Behind every closing is a carefully coordinated process involving escrow, title, lenders, and legal documentation—all working together to ensure ownership is transferred securely and funds are distributed correctly. Knowing what happens during the final stretch can help you approach closing day with confidence.

So, When Does a Home Seller Get Paid?

The short answer: after the transaction has officially closed and ownership has transferred to the buyer. While the exact timing can vary slightly depending on where you’re selling, most sellers receive their proceeds once all closing requirements have been completed and the sale has been recorded.

Here’s what happens between accepting an offer and receiving your funds.

Step 1: Accept an Offer

Once you and the buyer sign a purchase agreement, you’re officially under contract. The buyer will typically submit earnest money, which is held in escrow while the transaction moves forward.

Although the sale is underway, you won’t receive your proceeds at this point. There are still several important steps before closing day.

Step 2: The Transaction Moved Through Escrow

Escrow acts as a neutral third party that helps coordinate the transaction from contract to closing. During this time, the buyer may complete inspections, secure financing, satisfy contingencies, and work with their lender to finalize the loan.

At the same time, the title company verifies that the property’s ownership can be transferred without any outstanding legal issues, while escrow prepares the documents and financial details needed for closing.

Step 3: Closing Documents Are Signed

As closing day approaches, both the buyer and seller sign the documents needed to complete the transaction. For sellers, this generally includes signing the deed and paperwork required to transfer ownership. Buyers will sign their loan documents and finalize financing with their lender.

While signing is an exciting milestone, it doesn’t always mean you’ll receive your proceeds immediately. One final step still needs to happen before the transaction is officially complete.

Step 4: The Sale is Recorded

After all documents have been signed and the buyer’s funds have been received, the sale is recorded with the appropriate local government office. Recording is the legal transfer of ownership from the seller to the buyer.

Once recording is complete, the transaction is officially closed, and escrow can distribute the funds.

Wet Closings vs. Dry Closings

Depending on where you’re buying or selling, you may hear the terms wet closing and dry closing. The difference comes down to when the buyer’s loan is funded and when the seller receives their proceeds.

In a wet closing, all documents are signed, and the buyer’s loan is funded before the transaction officially closes. Once the sale is recorded, the seller’s proceeds are typically released shortly afterward, often on the same day.

In a dry closing, the closing documents may be signed first, but the buyer’s loan funding or final document review happens afterward. Because of this, there may be a delay of one to three business days before funds are released, and the buyer receives the keys. While it may extend the timeline slightly, a dry closing provides lenders with additional time to review documents, verify funding, and resolve any last-minute issues before the transaction is finalized.

Dry closings commonly occur because of lender funding timelines, pending document review, or regional real estate laws. The states that practice dry closings include Alaska, Arizona, California, Hawaii, Idaho, Nevada, New Mexico, Oregon, and Washington.

Whether your transaction is wet or dry closing depends on local regulations, lender requirements, and customary practices. Your real estate agent and escrow officer can help you understand what to expect.

How Do Sellers Receive Their Money?

Once the transaction has closed, sellers generally receive their proceeds through a wire transfer directly to a bank account or with a cashier’s check.

Before the funds are distributed, escrow also pays off any remaining mortgage balance, along with commissions, taxes, agreed-upon credits, and other closing costs. The remaining balance is your net proceeds.

How Long Does It Take to Get Paid?

In many transactions, sellers receive their proceeds on the same day the sale is recorded. However, the exact timing can vary depending on the escrow company, county recording schedule, and your financial institution.

If your proceeds are sent by wire transfer, they may arrive later that day, or in some cases, on the next business day.

The Bottom Line

While accepting an offer is an exciting milestone, it’s only one step in the home selling process. The transaction isn’t officially complete until the necessary documents have been signed, the sale has been recorded, and escrow has distributed the funds.

Having an experienced real estate agent by your side can make each stage of the closing process feel more manageable. If you’re preparing to sell your home, a Windermere agent can guide you through every step and help ensure you know what to expect.

Real Estate News & Information August 6, 2026

Private Listings Are Creating a Buyer Problem. How Will We Solve It?

by OB Jacobi

This article was originally published by Inman News on July 27, 2026. 

The House Judiciary Subcommittee on the Administrative State, Regulatory Reform, and Antitrust just sent letters to Compass CEO Robert Reffkin and Midwest Real Estate Data (MRED) CEO Rebecca Jensen, demanding briefings on the companies’ private listing partnership. Congress wants to know whether the deal – which pushes Compass’s “Private Exclusives” and “Coming Soon” listings nationwide through a database built for regional use – amounts to anticompetitive conduct.  

Lawmakers highlighted concerns that private listing networks could fragment inventory, weaken price competition, and build “velvet ropes” around homes, shutting out anyone not already inside the right circle of agents and buyers. 

It’s a moment our industry should welcome. But buried almost as an aside in the subcommittee’s letter is a troubling question: whether these partnerships incentivize agents to steer sellers toward private listings so a brokerage can represent both sides of a deal, or as the letter noted, “capture” buyers who contact the listing agent directly.  

Read that again. Congress isn’t only asking whether Compass has gotten too big. It’s asking whether buyers are being funneled toward whichever agent benefits the brokerage, rather than the one who actually serves them.  

That is a buyer problem, and it deserves to be treated like one. 

An incomplete story 

For months, the industry’s defense of private listing networks has centered almost entirely on the seller. Sellers benefit from privacy, sellers deserve choice, and full transparency exposes them to unfair judgment over how long a home quietly sat unsold.  

Given this congressional inquiry, a Consumer Federation of America request that the DOJ investigate the same partnership, an ongoing Zillow lawsuit alleging collusion, and a New York Attorney General probe into the Compass-Anywhere merger, you’d think the industry might finally widen the lens. 

Instead, the same seller-centered defense keeps getting pushed. Missing from nearly every version of this narrative is the party that is actually being squeezed out of the market: the buyer 

The buyer is already losing ground 

The National Association of Realtors’ own 2025 Profile of Home Buyers and Sellers tells a sobering story. First-time buyers made up just 21% of all purchasers this year, the lowest share NAR has recorded since it began tracking the data in 1981, and roughly half the historical norm of about 40% before the 2008 crash. The typical first-time buyer is now 40 years old, an all-time high, up from the late 20s a generation ago, and NAR’s own research leadership notes that delaying a first purchase by a decade can cost a buyer roughly $150,000 in lost home equity over time. That is not a market functioning normally. That is a generation of would-be buyers, including younger families, first-generation wealth builders, and renters trying to break in, all being pushed further to the margins. Into that environment, some brokerages want to normalize keeping listings quiet, curated, and shared selectively before the broader buyer pool ever sees them. It makes no sense. 

“Seller choice” has been weaponized 

The justification usually offered is seller choice. Some sellers simply prefer privacy, and in select cases that’s true and justifiable. But when you look at what’s actually driving the rise of private and pre-marketed listings, seller demand isn’t the obvious explanation. Independent surveys of agents have found that the overwhelming majority – roughly seven in ten – say no client has ever actually asked them to market a home privately.  

If sellers didn’t drive this tactic, it’s worth asking who benefits. The answer is the brokerage. A private or pre-marketed listing gives the listing brokerage a longer runway to also produce the buyer, collecting both sides of the commission before the property is exposed to the full marketplace. That’s not seller protection, it’s a business model, and buyers absorb the cost in reduced access and information. Interestingly, the metrics also show private sales tend to hurt the seller too, by leaving money on the table, which is why I see private listing networks as a perfect lose/lose. Neither the seller, nor the information-starved buyer, benefit. 

Consumer advocates are noticing, and now so is Washington 

This isn’t a fringe concern. A recent report from the Consumer Federation of America, produced with the National Urban League and drawing on a survey of housing counselors across dozens of states, flagged pocket and private listings as an emerging threat to fair and equal access to housing. Civil rights advocates have raised similar alarms for years. A marketplace that lets some buyers in early and keeps others out isn’t just inefficient, it can reproduce the very access barriers our industry has fought to dismantle. Congress asking hard questions is a good start, but they shouldn’t stop at market concentration, they should extend to every buyer who never got a fair look at a home because they weren’t plugged into the right network. 

Transparency isn’t a threat to sellers, it protects everyone 

At Windermere, we don’t believe that transparency and strong seller outcomes are in conflict. A well-informed marketplace, where buyers trust they’re seeing the full picture, produces more competitive offers and more durable transactions for sellers and buyers alike. And skilled real estate professionals should not need to rely on the artificial suppression of public inventory and market data to do their jobs. That’s why we’ve taken concrete steps to make sure our own listings clearly disclose their marketing history, so buyers aren’t left guessing what’s been withheld.  

As lawmakers dig into the Compass-MRED partnership, I hope they ask the question our industry keeps avoiding, not just whether this arrangement makes one brokerage too powerful, but whether it leaves buyers with less information, less access, and less leverage than they deserve.  

The industry can keep telling a story where sellers are the only ones at risk. Or it can look honestly, finally, at who’s actually being locked out of the market right now. First-time buyers aren’t disappearing because the market is transparent. They’re disappearing because, in too many ways, it isn’t. 

Buyers August 4, 2026

Pros and Cons of Buying New Construction

For many buyers, there’s something exciting about being the first person to live in a home. New construction offers modern layouts, updated finishes, and the opportunity to start fresh without taking on someone else’s renovation projects. While buying a newly built home has plenty of advantages, it also comes with a few tradeoffs that are worth considering before you make an offer.

Whether you’re comparing a brand-new home to an existing property or simply exploring your options, understanding the benefits and potential drawbacks can help you make a more informed decision.

The Benefits of Buying New Construction

One of the biggest reasons buyers choose new construction is that everything is designed with today’s lifestyle in mind. Many newly built homes feature open-concept floor plans, spacious kitchens, dedicated home office space, walk-in closets, and flexible living areas that can easily adapt as your needs change.

Because every component of the home is brand new, maintenance costs are often lower during the first several years of ownership. Instead of budgeting for the replacement of an aging roof, outdated plumbing, or an older furnace, many homeowners can spend more time enjoying their new space and less time worrying about repairs.

New homes are also generally more energy efficient than older properties. Modern insulation, high-performance windows, efficient HVAC systems, ENERGY STAR® appliances, smart thermostats, and other connected home technology can reduce utility costs while adding everyday convenience through features like smart locks, video doorbells, and integrated security systems.

Many builders also include warranties covering workmanship, major systems, and structural components for a specified period after closing, providing added peace of mind in case issues arise after you move in. And if you’re purchasing before construction is complete, you may have the opportunity to personalize finishes such as flooring, cabinetry, countertops, paint colors, and lighting to better reflect your style.

Perhaps one of the most appealing benefits is that a new home is truly move-in ready. Everything is clean, unused, and built to current building codes and standards, meaning you likely won’t need to plan for immediate renovations or major updates after closing.

Potential Drawbacks of Buying New Construction

One of the biggest considerations is cost. New homes often carry a higher purchase price than comparable resale homes, and the advertised base price doesn’t always include everything you see in the model home (if located within a new construction development). Premium flooring, upgraded cabinetry, designer lighting, landscaping, appliances, and lot premiums can quickly increase the final purchase price.

Timing can also be a factor. If the home hasn’t been completed yet, construction schedules may change due to weather, labor shortages, permitting delays, or supply chain delays. Buyers who need to move on a specific timeline may find that an existing home offers more certainty.

When buying in a new community, there are some additional factors to consider. While the homes themselves may be complete, neighborhoods can take years to fully mature. Landscaping is still growing, trees are often smaller, construction may continue nearby, and community amenities such as parks, clubhouses, or walking trails may still be under development. Lot sizes are another consideration. Many newer developments maximize land use by placing homes closer together than older neighborhoods, which can mean smaller yards and less outdoor space.

When it comes to negotiating, builders typically have less flexibility on the purchase price of the home than individual sellers do. Instead of reducing the asking price, they may offer incentives such as closing cost assistance, financing promotions, appliance packages, or design upgrades.

Finally, many new developments include homeowners’ associations (HOAs). In addition to monthly dues, HOAs may establish guidelines for landscaping, exterior paint colors, parking, fencing, and other aspects of the property. Understanding those rules before purchasing can help ensure the community is a good fit for your lifestyle.

Is Buying New Construction Right for You?

There’s no one-size-fits-all answer. The right choice ultimately depends on your priorities, budget, and long-term goals.

New construction may be an excellent option if you’re looking for a move-in-ready home with modern features, lower maintenance requirements, improved energy efficiency, and the opportunity to personalize finishes before moving in. It can be especially appealing if you plan to stay in the home for several years and want the convenience of starting fresh.

On the other hand, an existing home may be a better fit if you value mature neighborhoods, larger lots, distinctive architectural character, or greater flexibility when negotiating price. Resale homes can also offer advantages for buyers who need to move quickly or have a more limited budget.

No matter which path you choose, understanding the tradeoffs between new construction and existing homes can help you feel more confident throughout the buying process.

Living July 30, 2026

6 Commonly Missed Cleaning Spots

It’s easy to get into a routine when cleaning your home season after season, year after year. While simply going over the same spots may make your home feel cleaner, at the same time, it allows the neglected areas to become dirtier. Here are six commonly missed spots around the home that, once given the attention they deserve, will help make your home feel completely clean.

6 Commonly Missed Cleaning Spots

1. Underneath & Behind Furniture

Dirt and dust love to hide in tough-to-reach, tucked-away spots like behind your nightstand, under your bed frame, and on the underside of your tables, chairs, and couches. Cleaning these areas may require some heavy lifting and rearranging but it’s worth your while. If enough dust and grime have accumulated over the years that your vacuum can’t remove the buildup, try using a washcloth to loosen the sediment.

2. Vents and Fans

Vents and fans not only collect dust, but they also distribute it around your home. Ceiling fans are one of the hardest spots in your home to reach, so you may need to use a ladder and an extended duster to clean them. Clean your vent grates with a dusting brush or a wire brush depending on the thickness of the buildup. If your home has central air, remember to replace your air filters periodically. A clean ventilation system is key to protecting your home’s air quality.

3. Bathroom Surfaces

We all know the feeling of picking up a rarely used shampoo bottle in the shower to discover a grimy ring underneath it. Wipe off your bottles and surfaces in the shower to keep it sparkling clean. Scrub away the debris from your shower head and soak it in a mixture of water and white vinegar to cleanse the device and to prevent a buildup of mineral deposits. To reach behind the toilet, you may need knee pads and an extended cleaning tool. Use a disinfectant-water mixture to prevent the spread of germs. Tackling chores like these will help make your bathroom feel brand new in no time.

4. Switches & Handles

Light switches, door handles, drawer pulls, and knobs are all hotbeds for germs and dirt and can easily be forgotten while cleaning your home. Take a two-step approach to cleaning these high-touch surfaces: first clean, then disinfect. Cleaning will get rid of contaminants, while disinfecting targets pathogens. The combination of the two will help make your home feel cleaner while reducing the spread of germs. Other high-touch surfaces such as keyboards, phones, tablets, and other devices require regular cleaning as well.

5. Appliances

It’s easy to think of your appliances strictly as devices that help your home stay clean and organized, but they are magnets for dirt and gunk, too. After cleaning out the refrigerator and scrubbing down the shelves, find the coils and clean them of debris with a vacuum or a brush. The floor underneath your refrigerator can be a seriously grimy spot, so a quick mop of that area is worth your while. Give your dishwasher a good cleanse to prevent mold buildup and bad odors. Remember to clean out the filter occasionally with soap and water. Cleaning your appliances routinely can help avoid repairs and can even extend their life expectancy.

6. Baseboards

Baseboards are the perfect settling point for dirt and dust. The space between your walls and floors is an easy trap for buildup, and upon closer inspection, you’ll find some combination of scuffs, dust, food remnants and scratch marks. To thoroughly clean your baseboards, you may need to move your furniture away from the walls but be careful not to scratch the floor or damage the baseboards. Wipe away the dust before cleaning the surface. Use either a mix of soap and water, water and vinegar, or the proper wood cleaner for wooden baseboards.

Real Estate News & Information July 28, 2026

High Rates, Prices Drive King County Buyers Toward Adjustable-Rate Mortgages

King County homebuyers are increasingly turning to adjustable-rate mortgages to reduce their monthly homeownership costs. With the county’s median home price approaching $1 million and mortgage rates stubbornly above 6%, the affordability pressures driving this trend continue to grow.

Unlike traditional fixed-rate mortgages, adjustable-rate mortgages start with a lower interest rate that remains fixed for an initial period of several years before adjusting with the market. That lower starting rate is the primary draw for buyers looking to reduce their monthly payments.

In 2025, 36% of King County home purchases involved an adjustable-rate mortgage. Across Washington, adjustable-rate mortgages made up nearly a quarter of home loans, the highest share the state has seen since 2007. With mortgage rates on the rise again due to inflationary and political pressures, and no Federal Reserve cuts expected, experts say that share is likely to keep climbing.

Adjustable-rate mortgages are typically 0.5% to 1% lower than conventional fixed-rate mortgages, totaling a minimum savings of roughly $244 per month on a $750,000 loan at today’s rate. In King County, where prices routinely exceed that figure, the savings can be even more significant.

Many buyers are betting that rates will fall before their fixed period ends, allowing them to refinance, or plan to sell before their rate adjusts at all. Industry experts describe it as a relatively low-risk approach for buyers who do not expect to stay in their home beyond the typical seven-year window.

Adjustable-rate mortgages carry a stigma from the 2008 financial crisis, when they played a central role in a wave of foreclosures. Lenders at the time offered extremely low introductory rates lasting only two or three years and approved practically anyone regardless of their ability to repay. By 2004, these loans made up half of all home loans in Washington. When borrowers could not afford the higher rates, the fallout reshaped the housing market for years.

Today’s adjustable-rate mortgages are a different product entirely. Lenders must now verify that borrowers can afford the loan at higher post-introductory rates, initial fixed periods are longer, and rate discounts are more modest, making the kind of payment shock that defined the 2008 crisis far less likely.

With ongoing affordability concerns statewide and across King County, adjustable-rate mortgages offer a way to reduce the initial cost of the loan. In large part, their increasing popularity stems from the growing gap between home prices and what many borrowers can afford.

This post was based on information found on Puget Sound Business Journal.

SOLD July 23, 2026

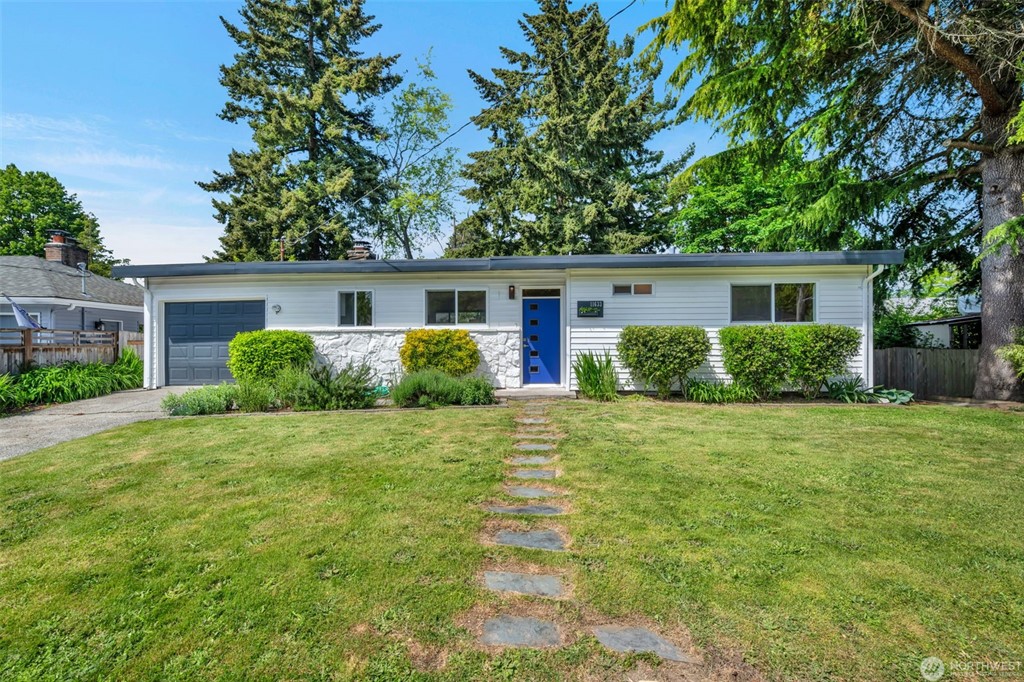
SOLD: Rare 5-BR, 2200-SF, 2-Level Shorewood Home

HELPED BUYERS GET UNDER CONTRACT

11633 18th Avenue SW
Burien, WA 98146
Sold: $775,000

  • Beds: 5
  • Baths: 2
  • Size: 2,200 sqft
  • Year Built: 1960
  • Lot Size Area: 7,200.00 sqft
  • Garage Spaces: Yes
  • Heating: Heat Pump
  • Cooling: Central Air, Heat Pump
  • County/Parish: King
  • Subdivision: Shorewood
  • MLS #: 2528701
  • CLIP #: 2605605269

Rare 5-bedroom, 2200 SF two level home located in the desirable Shorewood neighborhood. Spacious entry leads to the great room with hardwood floors, fireplace, oversized windows, and dining room space. The kitchen features expansive granite countertops, ample cabinet and storage space, and newer Energy Star certified stainless steel appliances. The primary bedroom is on the main floor along with two additional bedrooms and a full bathroom. The lower level features a family room with second fireplace, office space, two more bedrooms, and a second full bathroom. Includes a large storage room and laundry room. Walk out to the patio and generous backyard featuring a large stone fireplace, beautiful trees and tiered lavender garden. Storage shed and one-car garage ensure nothing needs to be left outside. Conveniently located near the scenic trails and shorelines of Seahurst, Lincoln and Westcrest Parks. Just minutes from Burien, White Center, and West Seattle for a diverse array of shopping and dining. Easy freeway access to downtown, SeaTac and just around the corner from the Rapid Ride H line. The neighborhood block parties are not to be missed!


Real Estate Listings July 21, 2026

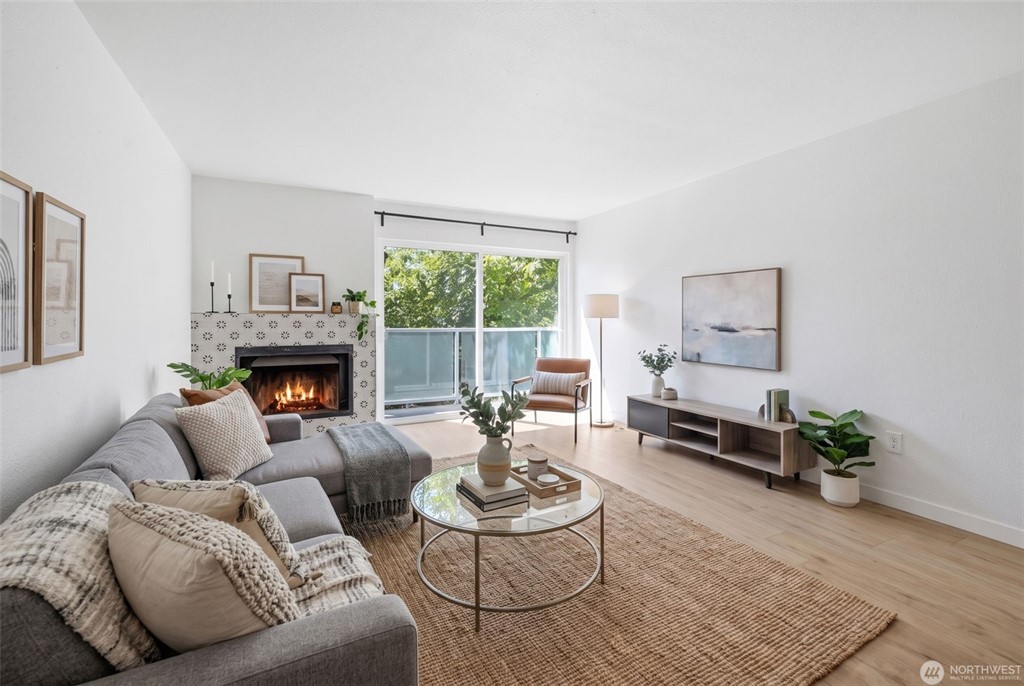
NEW LISTING: Rare Townhome-Style Condo in Maple Leaf

8800 20th Avenue NE #B202
Seattle, WA 98115
Listed: $440,000

  • Beds: 2
  • Baths: 2
  • Size: 1,098 sqft
  • Type: Condominium
  • Year Built: 1979
  • Heating: Baseboard, Forced Air
  • Cooling: None
  • HOA Fee: $637 Monthly
  • Pets Allowed: Cats OK
  • County: King
  • Subdivision: Maple Leaf
  • MLS #: 2553608
  • CLIP #: 4202152358

Rare townhome-style condo offering the perfect blend of privacy, sophisticated design, and an unbeatable Maple Leaf location. Thoughtfully remodeled with quartz countertops, premium appliances, luxury vinyl plank flooring, and a cozy fireplace, this home is enhanced by Philips Hue smart lighting, smart thermostats, skylights, and a private balcony. The sunlit loft creates the ideal home office or flex space, while custom PAX closet systems, abundant storage, a Miele washer & dryer, dedicated storage unit, and parking add everyday convenience. Well-managed HOA with no upcoming special assessments. Minutes to Maple Leaf Reservoir, Green Lake, University Village, light rail, dining, shopping, and I-5.

Click here for more information.

Sellers July 16, 2026

Home Appraisals Explained: What Sellers Should Expect

If you’re selling your home, there’s a good chance you’ll hear the word appraisal shortly after accepting an offer. While it may feel like just another step in the transaction, a home appraisal plays an important role in many home sales, especially when a buyer is financing their purchase with a mortgage.

For many sellers, the appraisal process can feel daunting and mysterious. Who orders it? What does the appraiser actually look at? And what happens if the home appraises for less than the agreed-upon purchase price?

Understanding what happens during a home appraisal can help you prepare your home, set realistic expectations, and navigate the process with confidence. Here’s what every seller should know.

What Is a Home Appraisal?

A home appraisal is an independent evaluation of a home’s current market value conducted by a licensed appraiser. In most financed home purchases, lenders require an appraisal before approving the buyer’s loan to verify that the property’s value aligns with the amount they’re lending.

Although the buyers generally pay for the appraisal as part of their closing costs, the appraiser’s responsibility is to the lender. Their job is to provide an objective opinion of the home’s value by evaluating the property itself and comparing it to similar homes that have recently sold nearby.

When Does the Appraisal Happen?

Once a seller accepts an offer and the purchase agreement is signed, the buyer’s lender will usually order the appraisal early in the transaction. The timing can vary, but it typically occurs within the first few weeks of escrow.

The appraiser will coordinate a time to visit the property. While sellers don’t necessarily need to be present during the appointment, someone will need to provide access to the home. After the inspection, it may take several days for the completed appraisal report to be delivered to the lender.

What Does an Appraiser Look For?

During the visit, the appraiser evaluates both the home’s condition and the features that contribute to its market value. They also consider recent sales of comparable homes in the area, often called “comps”, to help determine how your home compares to similar properties in the current market.

They’ll typically examine:

  • Overall size and layout
  • Number of bedrooms and bathrooms
  • Interior and exterior condition
  • Quality of construction finishes
  • Major systems such as the roof, HVAC, plumbing, and electrical
  • Recent renovations or improvements
  • Lost size and usable outdoor space
  • Garage, parking, or additional structures
  • Energy-efficient features or notable upgrades

The appraiser also takes photographs and measurements of the property to include in the final report. It’s important to remember that an appraisal isn’t the same as a home inspection. While inspectors look for potential defects or maintenance issues, appraisers focus primarily on determining the home’s market value based on its quality and features.

Can Sellers Prepare for an Appraisal?

While sellers can’t control the final valuation, they can take several steps to present the home in its best light.

  • Complete small repairs
  • Finish ongoing projects
  • Improve curb appeal
  • Clean and declutter
  • Create a list of improvements

What Happens If the Appraisal Comes in Low?

If the appraised value meets or exceeds the purchase price, the transaction typically moves forward as planned. The buyer’s lender now has confirmation that the property’s value supports the loan amount, allowing financing to continue toward closing.

A low appraisal doesn’t automatically mean the sale is over, but it may require additional conversations between the buyer and seller. Some possible outcomes include:

  • The buyer covers the difference
  • The seller reduces the price
  • Both parties negotiate
  • The buyer challenges the appraisal
  • The transaction doesn’t move forward

While a low appraisal can feel discouraging, an experienced agent can help you understand the results, explain your options, and work with all parties to determine the best path forward.

Whether you’re preparing to sell or simply exploring your options, a Windermere agent can help you understand your home’s value, navigate changing market conditions, and guide you through every step of the selling process.

Real Estate News & Information July 14, 2026

Local Market Update – July 2026

Inventory continued to grow across all four of our local market areas in June, creating a more balanced environment than we’ve seen in recent years. Compared to June 2025, home prices softened in each market area, and buyers are benefiting from increased selection and more negotiation power. Well-prepared, competitively priced homes continue to attract strong interest, so seller strategy matters more than ever.

KING COUNTY 

King County continued its transition toward a more balanced market as active listings increased 16% year over year. The additional inventory likely contributed to the 5% decline in the median residential sold price, bringing it to $986,250. As buyers gained options, sellers showed more flexibility, with nearly one-third of homes selling after a price reduction. Pending sales slipped 8% from a year ago, a sign that buyers are active but more selective. In the condo segment, the median price dropped 11% while active listings increased 18%.

SEATTLE

In June, Seattle remained one of the more competitive markets in the region, even as conditions continued to balance out. Active listings increased just 3% year over year, the smallest bump among our four market areas. The median residential sold price fell to $1,010,000, down 6% from last year and 3% from May. Well-positioned homes remained in demand, with 30% selling above asking price and 80% going under contract within 30 days. At the same time, buyers were more deliberate and patient than in years past, and pending sales dropped 11% while closed sales fell 7%. The condo market followed similar trends, with the median price dropping 5% to $557,475 as active listings rose 9%.

EASTSIDE 

The Eastside posted the region’s largest inventory gain in June, with active listings climbing 29% year over year. Available inventory reached 3.3 months of supply, a new 10-year high. The median price for a single-family home edged down 3% year over year to $1,560,000. Sellers adjusted to lowering prices and growing inventory, with nearly 40% of sales closing only after a price reduction. Buyers acted quickly: 78% of homes sold within 30 days. Pending sales declined 9% year over year, highlighting the importance of preparation and pricing. Eastside condos followed the same pattern, with the median price down 11% and active listings up 29%.

SNOHOMISH COUNTY

Snohomish County stood out last month as the only one of our four markets with year-over-year increases in both pending sales and closed sales, rising 8% and 3%, respectively, even as active listings rose 26%. The median residential sold price settled at $750,000, down 8% from last year and 6% from May. Sellers adapted to the shift, and 32% of homes sold after a price adjustment. Buyer activity remained high, with nearly three-quarters of homes going under contract within 30 days. In the county’s condo market, the median price fell nearly 20% to $487,500 as active listings increased 43%.

LOOKING AHEAD

As we move through the heart of summer, inventory growth continues to reshape our local housing market. Buyers are gaining options and leverage, while sellers who price strategically and prepare their homes thoughtfully are achieving the strongest results. Although elevated interest rates and affordability challenges will likely influence buyer decisions in the months ahead, today’s more balanced market creates opportunities on both sides of the transaction. An experienced Windermere advisor can help you understand local conditions, identify opportunities, and develop a strategy aligned with your real estate goals.

Read more.