Buyers • July 2, 2026

What is a Buyer’s Market?

Much can be determined about the conditions of a local real estate market by examining supply and demand. When the supply of available homes exceeds buyer demand, it’s known as a buyer’s market. Reduced listing prices, longer days on market, and an increase in price reductions are all common signs of a buyer’s market.

While market conditions can vary widely by region, neighborhood, or price point, understanding how a buyer’s market works can help you navigate your home search when opportunities arise.

What is a Buyer’s Market?

A buyer’s market creates favorable conditions for those looking to purchase a home. With more homes available than active buyers, sellers often face increased competition for attention. This gives buyers more options and, in many cases, greater flexibility throughout the home buying process.

In a buyer’s market, inventory levels tend to be higher, allowing buyers to take more time to compare homes and identify the right fit. Properties often remain on the market longer, and sellers may be more willing to adjust pricing or offer concessions to attract qualified buyers.

It’s important to remember that real estate markets are local. Even when broader market conditions favor buyers, some neighborhoods or property types may remain highly competitive.

To better understand what’s happening in your area, connect with a Windermere agent for insight into local inventory, pricing trends, and market activity.

How to Approach a Buyer’s Market

While a buyer’s market can create advantages, having a clear strategy remains important. Buyers often can be more selective, carefully comparing homes and evaluating their options without the urgency that typically accompanies a seller’s market.

A buyer’s market can also create favorable conditions for negotiations. With fewer active buyers competing for homes, sellers may be more willing to negotiate on price, closing costs, repairs, or other terms. This is one reason why working with a buyer’s agent can be especially valuable. An experienced agent can help identify opportunities, navigate negotiations, and guide you through each stage of the buying process.

If you’re selling your current home while searching for your next one, you may have a better chance of including a home-sale contingency in your offer. While contingent offers are often challenging to secure in highly competitive markets, sellers may be more receptive when buyer demand is lower. When structured properly, a contingency can provide added flexibility by allowing you to complete the sale of your current home before moving forward with a purchase.

Homes that have been on the market for an extended period can also present opportunities. Longer listing times may indicate that sellers are more open to negotiating. However, buyers should still work closely with their agent to evaluate the home’s value and develop a competitive offer strategy.

In many buyer’s markets, sellers take extra steps to make their homes stand out. This can include completing repairs, making updates, improving curb appeal, or offering incentives to attract buyers. As a result, buyers may have additional leverage when negotiating repairs or requesting concessions during the inspection process.

Even in a buyer’s market, preparation remains key. Having your financing in order, understanding your budget, and working with a knowledgeable real estate professional can help you act confidently when you find the right home.

Buyers • June 29, 2026

Planning Ahead: A 12-Month Guide to Buying Your First Home

Thinking about buying a home can be daunting, especially if it’s your first time. What should be an exciting milestone can feel overwhelming without a clearly defined roadmap, and diving in headfirst without a solid plan can lead to unnecessary stress, financial surprises, and missed opportunities. However, by establishing a timeline and breaking the process down into manageable steps, you can move forward with confidence and clarity.

Here is your month-by-month guide to preparing for a successful home purchase in the following year.

12 – 10 Months Out

Know Your Why

Understand your motivation for buying. Are you relocating, growing your household, or ready to invest in your future? Clearly defining your “why” will help shape your search criteria and influence your budget, location, and timeline.

Set Clear Goals

Start to think about what you want in your new home. Create a list of your wants versus must-haves, including location, budget, size, and style of home. These goals will act as a compass throughout your search. Be sure to include your ideal timeline and what you hope to get out of the overall experience.

Find an Agent That Prioritizes Your Goals and Timeline

A trusted real estate agent is more than just a facilitator; they’re a guide, negotiator, and advocate. Look for someone who understands your timeline and long-term vision and is familiar with the local market. Ask them to provide a first-time buyer’s guide or checklist to help you get started. Building this relationship early allows your agent to understand your needs and preferences in advance, setting the stage for a smoother process when you’re ready to make your move.

9 – 7 Months Out

Assess Your Finances

Take a close look at your income, debt, and spending habits. Use this time to create a monthly budget that includes future mortgage payments, utilities, insurance, taxes, and home maintenance. Many experts recommend spending no more than 28% of your gross monthly income on housing costs.

Boost Your Credit

Your credit score has a significant impact on your buying power, including your mortgage rate and loan approval. Take the next few months to pay down high-interest debt, stay current on all payments, and avoid opening new credit accounts. Check your credit report for errors and work on improving your score if needed.

Start Saving

You’ll want to have enough set aside not only for a down payment, which is typically 3% to 20% of the purchase price, but also for closing costs, moving expenses, and initial home repairs or furnishings. During this time, try to avoid nonessential major purchases and think about setting up a dedicated home savings account to stay consistent.

6 – 4 Months Out

Talk to a Financial Advisor

A financial advisor can help you align your financial goals with your homebuying plans. They can offer advice on what you can realistically afford and help identify areas to strengthen your financial readiness. You can also use tools like an online mortgage calculator to get a clearer idea of what your future monthly payments might look like.

Research Homebuyer’s Courses & Guides

Take advantage of first-time homebuyer resources, guides, and online courses. The more you know earlier on, the more confident you’ll feel.

3 – 2 Months Out

Familiarize Yourself with the Market

Start browsing homes and monitoring prices in the neighborhoods you’re interested in. Learn whether your local market is currently favoring buyers or sellers and what that could mean for your strategy.

Meet with a Lender and Get Pre-Approved

Meeting with a lender and getting pre-approved can help give you a clear picture of how much you can borrow and what price range to shop within. It also shows sellers that you’re a serious buyer when the time comes to make an offer. Your realtor can recommend trusted lenders to work with and assist you through this process.

Start Your Home Search

Now that you have your list of wants and needs and know your price range, you’re ready to start searching for your dream home. Use online property research tools to filter by location, features, and price to see what’s available in the locations you like. Narrow down your top homes and start scheduling showings and comparing listings.

1 Month Out

Make an Offer

Once you find “the one,” your agent will help you craft a competitive offer, negotiate terms, and guide you through contingencies.

Get a Home Inspection
If your offer is accepted, a licensed inspector will identify any issues with the property before you finalize your purchase. Depending on what comes up, this can give you leverage to negotiate repairs or price adjustments.

The Time Has Come

Closing On Your New Home
You’ve made it! During closing, you’ll sign paperwork, pay final costs, and receive the keys to your new home. Your agent and lender will walk you through the final steps to ensure everything goes smoothly.

Buying a home may seem like a big leap, but with a solid 12-month plan and the right support, it can be an extremely rewarding experience. Take it one step at a time and know that a trusted agent is here to help whenever you’re ready.

Living • June 25, 2026

Streamlining Your Life: 7 Tips to Make Downsizing Easier

Whether you’re retiring, moving into a smaller space, or simply want to live more minimally, downsizing can simplify the process. After all, the fewer belongings you have, the less you need to pack, move, and organize in your new place. But for many of us, the mere idea of downsizing can be daunting. How do you decide what to keep and what to let go of after accumulating a lifetime of possessions, mementos, and memories?

The secret, as it so often is, is to plan ahead. Here are some tips to make downsizing easier.

Start early:

Begin the downsizing process several months before your move date if you can. Starting early allows you to pace yourself and avoid last-minute rushes. It also gives you time to work through your emotions, so you’re less likely to keep something you don’t use simply because you’ve owned it for years.

Create a downsizing calendar:

Budget your time by dedicating specific days or weekends to different tasks, such as sorting through possessions, donating items, and dealing with recycling or disposal. Like a to-do list, a calendar can inspire action by giving you a clear agenda for each day or week.

As part of the process, research where to drop off items and their operating hours to improve efficiency. For example, you may need to schedule pickups or drop-offs for local charities or other organizations that accept donations. Also allow extra time if you’re posting items online, as they may take longer to sell.

Sample calendar:

  • Week 1: Sort through bedroom clothes and accessories.
  • Week 2: Declutter books and paperwork.
  • Week 3: Tackle the kitchen (utensils, appliances, etc.).
  • Week 4: Assess living room furniture and storage.
  • Weeks 5 and 6: Tackle the garage and/or basement.
  • Week 5: Organize garage sale or list items for sale online.
  • Week 6: Donate remaining items and arrange for recycling or disposal.

Develop criteria for making decisions:

When planning, factor in your reasons for downsizing, and use these as criteria when faced with difficult choices. For example:

  • If you’re simplifying: Keep items that bring you joy and get rid of items that cause stress. Prioritize items that add meaning to your life or hold sentimental value.
  • If you’re cutting costs: Consider getting rid of items associated with costly hobbies or that require expensive maintenance.
  • If you’re moving into a smaller space: Prioritize belongings you use regularly or that serve a practical purpose. Let go of items that are rarely used or have no clear function.

Sort items by their intended destination:

Designate specific areas for items you plan to keep, donate, sell, recycle, or dispose of. Use labels or colored markers to clearly mark each pile.

  • Keep: Items that fit your decision-making criteria (see above)
  • Donate: Items in good condition that others can use
  • Sell: Valuable items you don’t need but can convert into cash
  • Recycle: Items that are broken, outdated, or no longer useful, but that can be recycled
  • Discard: No longer useful items that can’t be recycled

Take it room by room:

Treat each room as a separate project. You may want to start with a smaller room that you’re less emotionally attached to, like a home office, to make decisions easier. Once you’ve finished each room, give yourself a pat on the back before moving to the next. Recognizing these smaller accomplishments can provide a mental boost as you work towards achieving your larger goal.

Consider off-site storage:

If you don’t have as much time as you’d like or have more valuable items than your new space will accommodate, consider renting an off-site storage unit. Some people use storage units for six months to a year after a move, allowing them to sort through their items at a more deliberate pace. This approach lets you gradually incorporate some items into your new living arrangement and decide what to do with the rest. However, be careful not to fall into the “out of sight, out of mind” trap. It’s easy to neglect a storage unit, only to realize years later you’ve made little progress.

Take time to reflect:

For many people, the hardest part of downsizing is letting go of belongings with sentimental value. Give yourself time to process the emotions tied to these items. Think of them as treasured memories rather than losses, and take photos of items you cherish but can’t keep. Shifting your perspective can also be helpful. This can be a liberating transition to a new lifestyle—one that’s more thoughtful about what’s worth holding onto. And remember, there are always new memories to be made!

Design • June 23, 2026

Pet Friendly Home Decor Ideas

For many of us, pets are important members of our household, which means our homes should be as comfortable for them as they are to everyone else who lives there. When choosing how to decorate your home, whether you’re moving into a new one or welcoming a new furry or feathered friend into the one you already live in, thinking ahead about their needs can not only create a happy space for everyone but also help with the inevitable pet-related accidents and other possible issues down the road.

Cuddly-friendly Furniture

While some pet owners refuse to let animals on couches or chairs, others love to cuddle with their furry friends on or near their laps. If you fall in with the first group, create a soft space on the floor for Fido or Fluffy to lie on when the family is relaxing. Dog and cat beds come in just about every material, color, and style you can imagine, so finding one that fits in with your aesthetic should be relatively simple.

If you’re in the second group, select furniture that can withstand the wear and tear of claws, accidents, and frequent vacuuming. Leather (or faux leather) surfaces are best for homes with animals that shed. If you prefer the feel of fabric instead, choose a couch or loveseat made from stain-resistant materials or use a washable slipcover.

Throw blankets are not only cozy, but they are also great for creating a barrier between pets and furniture, and they’re a lot easier to clean than an entire couch.

Safe Plants

Incorporating live plants and greenery is a great way to add a touch of nature to your home’s interior, but not all plants are safe for pets. While fake plants are an option, they don’t provide the extra benefit of helping to clean the air you breathe while indoors.

Rattlesnake plants, spider plants, orchids, many kinds of fern, and small palms are all beautiful additions that aren’t toxic if your pup or kitten takes a nibble. There are also many types of succulents that are pet-safe, and the spiny ones will deter a pet that’s looking for a snack or—in the case of some cats—a litter box.

Flooring

When it comes to pets, accidents are usually inevitable. As well behaved and trained as they may be, pets get sick, old, and stressed. Though messes are bound to happen, lingering stains don’t have to. Hardwood, tile, and vinyl floors make it easy to wipe up anything your pet leaves behind, as well as spills they may cause. Washable rugs come in dozens of attractive styles and are great at protecting floors, especially if you add a pet-proof pad underneath. Put plastic or vinyl mats under pet feeding areas to protect floors from spills and to prevent bits of food from spreading throughout the house.

Colors

The best way to camouflage pet hair in between sweeping and vacuuming is to select furniture, carpets, and décor items that match your pet’s coat. If you’ve got a brindle pup, calico kitty, or multi-colored animal friend, patterns will be your best bet. Florals, plaids, stripes, paisleys, and other patterns also help hide stains when those inevitable spills and accidents happen.

Hidden Essentials

Our animal buddies are sweet, cute, and cuddly, but not everything about having a pet is attractive. Litter boxes, feeding stations, and sleeping crates take up a lot of room and can be eyesores. Fortunately, furniture makers have taken notice and created pieces that are both aesthetically pleasing and functional.

For indoor kitties, litter boxes are necessary, but constantly seeing and smelling them isn’t. Get the box out of sight with a stylish litter box side table. Dogs can nap in style with a crate that doubles as an end table or nightstand. Feeding stations with storage make dinner time easy and keep unsightly bags of food hidden away.

Your love of animals doesn’t have to get in the way of living in style. These tips should help you find the right balance between the two.

Living • June 18, 2026

The Life Expectancy of Your Home

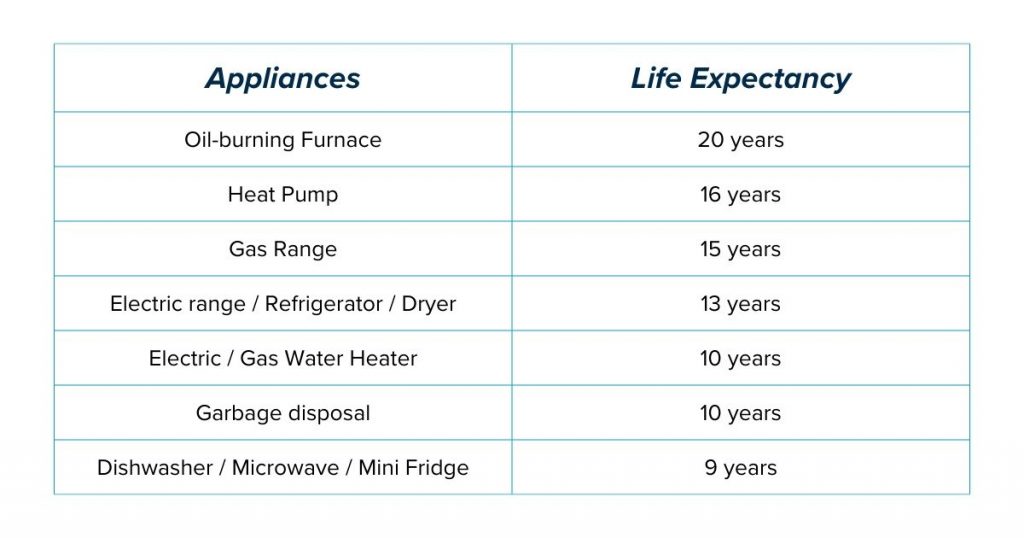
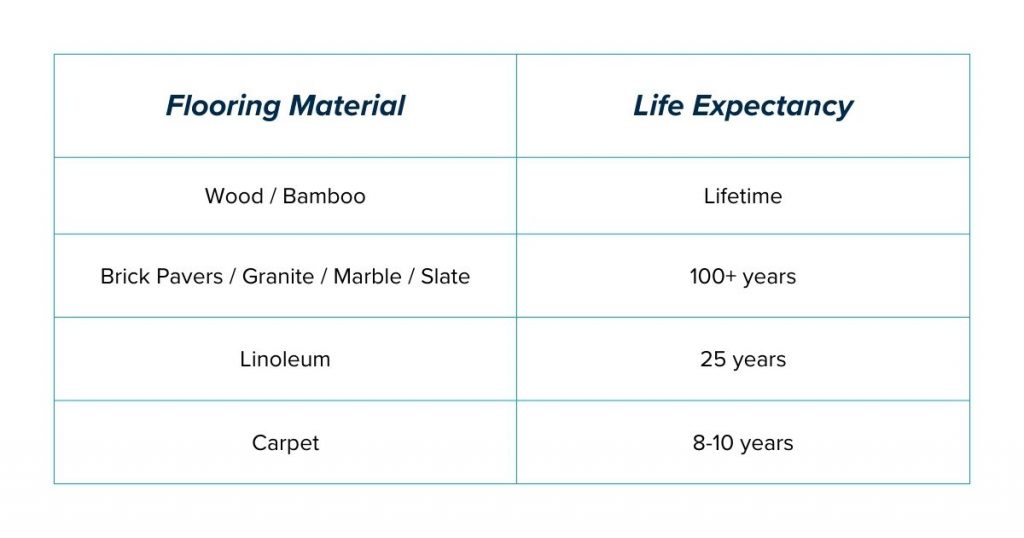
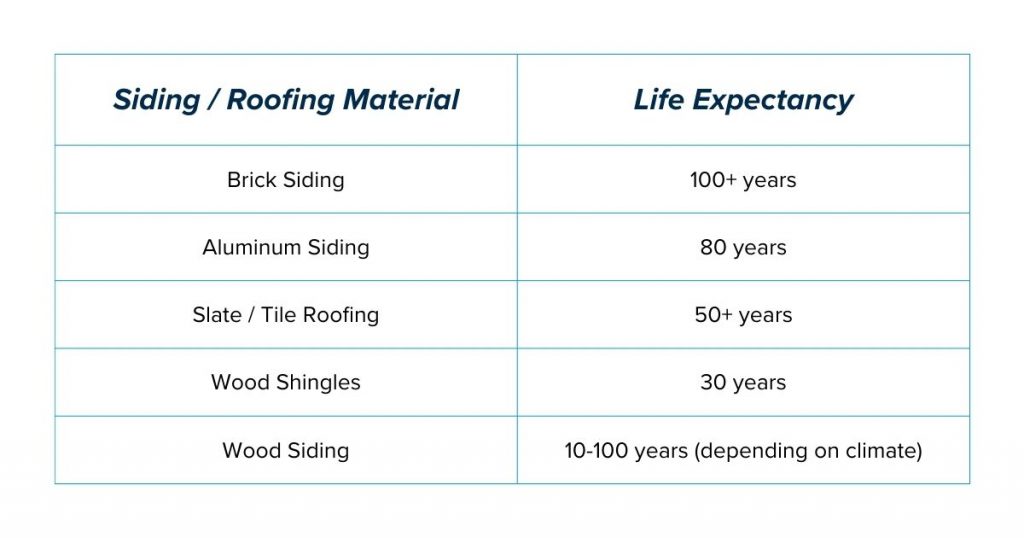
Every component of your home has a lifespan. Common questions asked by homeowners include when to replace the flooring or how long to expect their siding to last. This information can help when budgeting for improvements or deciding between repairing and replacing when the time comes. We’re all familiar with the cliché: They just don’t build things like they used to. And while this may be true when it comes to brick siding or slate roofing, lifespans of other household components have increased in recent years. Here are the life expectancies of the most common household items (courtesy of NAHB):

Appliances:

Among major appliances, gas ranges have a longer life expectancy than things like dishwashers and microwaves.
Chart describing the life expectancy on the most common household appliances.

Kitchen & Bath:

When choosing your countertops, factor in the life expectancies of different materials.

Flooring:

If you’re looking for longevity, wood floors are the way to go. Certain rooms in your home will be better suited for carpeting, but you can expect they’ll need replacing within a decade.

Siding & Roofing:

When choosing roofing and siding for your home, climate and maintenance level factor into the life expectancy of the material. However, brick siding and slate roofing are known to be dependable for decades.

Are extended warranties warranted?

Extended warranties, also known as service contracts or service agreements, are sold for all types of household items from appliances to electronics. They cover service calls and repairs for a specified time beyond the manufacturer’s standard warranty.

You will have to consider whether the cost is worth it to you. For some, it brings a much-needed peace of mind when making such a large purchase. Also consider if the cost outweighs the value of the item. In some cases it may be less expensive to replace a broken appliance than to pay for insurance or a warranty.

Real Estate News & Information • June 16, 2026

Local Market Update – June 2026

As spring draws to a close, our local housing markets continue to show a growing divide. Well-priced, well-prepared homes are selling quickly, and often for at or above asking price, while properties that miss the mark on pricing or presentation are spending more time on the market and seeing price reductions. Buyer activity remains steady despite higher inventory levels, creating a more balanced environment than we’ve seen in years. What makes today’s market particularly interesting is that pricing is no longer moving in the same direction across the region. Seattle continues to post price gains, while Eastside and Snohomish County prices have moderated from recent highs. Inventory is up and demand remains steady, but these dynamics have created a market where strategy and execution matter more than timing alone.  

KING COUNTY 

In King County, the median residential sold price dipped 1% year over year to $975,000 in May, reflecting a market that remains remarkably stable. Active listings continued to grow, rising 14% year over year and 15% month over month. Pending sales slipped 3% from a year earlier but increased 6% from April, suggesting buyer activity remained healthy as the spring market progressed. The market remained competitive for desirable homes, with roughly half of homes selling at or above asking price. In the condo segment, the median price declined 5% year over year to $540,000, while closed sales fell 20%. 

SEATTLE

Seattle delivered one of the strongest performances among our markets in May, with steady sales activity, moderating inventory growth, and continued price appreciation. The median sold price for a single-family home rose 3% year over year to $1,037,500. Active listings continued to expand, though at a more moderate pace than in recent months, increasing 2% from last year and 10% from April. Closed sales climbed 7% year over year, underscoring consistent buyer demand. Homes continued to move quickly, with the majority selling within 30 days and more than half selling at or above asking price. In the condo market, the median price slipped 1% to $566,600 while active listings increased 6%.

EASTSIDE 

On the Eastside, inventory and months of supply reached their highest May levels in more than a decade. Even with the increased supply, homes that were appropriately prepared and priced continued to perform well, with more than 40% selling at or above list price. The median residential sold price declined 8% year over year to $1,510,000. Active listings grew 27% from last year, but buyers continued to be selective, contributing to an 8% decline in pending sales. While these figures may suggest a cooling market, demand remains healthy for desirable homes. The Eastside is becoming more balanced rather than weak, giving buyers more options while still rewarding sellers who position their homes strategically. The condo market followed similar pricing and inventory patterns, with the median price falling 9% to $661,500, while active listings rose 17%.

SNOHOMISH COUNTY

While Snohomish County’s May prices stayed near historic highs, appreciation continued to moderate. The median sold price for a single-family home declined 4% year over year to $800,000. At the same time, the market recorded its highest May inventory level in a decade, creating greater competition among sellers. Active listings surged 32% from a year ago, and buyer demand remained resilient, with pending sales increasing 2% year over year. That combination suggests buyers are absorbing some of the new inventory coming online. In the condo segment, the median price rose 1% to $495,000 while active listings climbed 39%.

LOOKING AHEAD

As inventory levels continue to balance the market, buyers are benefiting from more choices and a less frantic market environment than in recent years. At the same time, demand remains strong enough that well-positioned homes are still selling quickly and often at or above asking price. Across our region, the gap between those listings and everything else continues to widen. Success in today’s market is less about trying to time the market and more about understanding local conditions, pricing strategically, and executing a thoughtful plan. Whether you’re buying, selling, or simply evaluating your options, working with a trusted Windermere advisor can help you navigate changing conditions and move forward with confidence.  

Read more.

Sellers • June 11, 2026

Staging for Home Selling Success

The benefits of staging a home are well documented. Numerous studies show that staging helps sell a home faster and for a higher price. Studies also indicate that buyers decide if they’re interested within the first 30 seconds of entering a home. Not only does home staging help to remove potential red flags that can turn buyers off, it also helps them imagine living there. Homes that are professionally staged look more “move-in ready,” which makes them far more appealing to potential buyers.

Ready to get started?

If you’re ready to put your house on the market and want to try your hand at staging, here are some concepts to keep in mind:

Aim for Cohesion

Make the inside match the outside. For example, if the exterior architectural style of your house is mid-century modern, the interior should be primarily outfitted with mid-century modern style furniture. Prospective buyers who like the exterior style of your home are going to expect something similar when they step inside. If the two styles don’t agree or at least complement each other, there is likely going to be an immediate disconnect for the buyer.

There is always room for flexibility. Not all your furnishings need to match, and even the primary furnishings do not need to be an exact match to the architectural style of your home. To create cohesion, you simply need to reflect the overall look-and-feel of the exterior.

Neutralize and Brighten

Every home is a personal expression of its owner. But when you become a seller, you’ll want to look for ways to make your home appeal to your target market. Keep in mind, your target market is made up of the group of people most likely to be interested in a home like yours—which is something your agent can help you determine.

A good strategy to staging your home is to “neutralize” the design of your interior. A truly neutral interior design allows people to easily imagine their own belongings in the space—and to envision how some simple changes would make it uniquely their own.

Paint over bold wall colors with something more neutral, like a light beige, warm gray, or soft brown. The old advice used to be, “paint everything white,” but often that creates too sterile of an environment, while dark colors can make a room look small, even a bit dirty. Muted tones and soft colors work best. Likewise, consider removing wallpaper if it’s a bold or busy design.

Lighting is key. Replace heavy, dark curtains with neutral-colored shear versions; this will soften the hard edges around windows while letting in lots of natural light. Turn on lamps, and if necessary, install lighting fixtures to brighten any dark spaces—especially the entry area.

Clean and De-Clutter

To further inspire buyers to imagine the space as their own, make sure every room—including closets and the garage—is clean and clutter-free. You may even want to hire professionals to give your home a thorough deep clean. Remember, the kitchen and bathrooms are by far the two most important rooms in a house when selling, so ongoing maintenance is important.

Family photos, personal memorabilia, and collectibles should be removed from the home for your safety. Closets, shelves, and other storage areas should be mostly empty. Work benches should be free of tools and projects. Clear the kitchen counters, store non-necessary cookware, and remove magnets from the refrigerator door.

The same goes for furniture. If removing a chair, a lamp, a table, or other furnishings will make a particular space look larger or more inviting, then do it.

You don’t want your home to appear cold, un-loved, or unlived-in, but you do want to remove distractions and provide prospective buyers with a blank canvas of sorts. Plus, de-cluttering your home now will make it that much easier to pack when it comes time to move.

Where to Start

If you’re concerned about the additional cost of staging, rest assured. Even a relatively small investment of time and money can reap big returns. There are even things you can do yourself for little to no cost. Contact your agent for advice on how to stage your home most effectively or for a recommendation on a professional stager. While the simple interior design techniques outlined above may seem more like common sense than marketing magic, you’d be surprised at how many homeowners routinely overlook them. And the results are clear: staging your house to make it more appealing to buyers is often all it takes to speed the sale and boost the sale price.

Sellers • June 9, 2026

Moving Checklist: A Step-by-Step Guide to the Moving Process

Moving is an exciting milestone, but it also comes with a long list of tasks and deadlines to manage, especially if you’re buying and selling a home at the same time. Whether you’re moving across town or across the country, staying organized can help make the process significantly less stressful.

From hiring movers and transferring utilities to packing essentials and settling into your new home, this step-by-step moving checklist will keep your move on track from start to finish.

A Step-By-Step Guide to the Moving Process

We’ve included a comprehensive checklist below of all the steps you’ll need to complete to ensure a smooth, successful move. This list is also available as an interactive web page and downloadable PDF here: Moving Checklist

Twelve Weeks Before:

  • Get estimates from professional movers or truck rental companies if needed.
  • Once you’ve selected a mover, discuss insurance, packing, loading and delivery, and the claims procedure.

Six to Eight Weeks Before:

  • Use up things that may be difficult to move, such as frozen food.
  • Sort through your possessions. Decide what you want to keep, what you want to sell, and what you wish to donate to charity.
  • Record serial numbers on electronic equipment, take photos (or video) of all your belongings and create an inventory list.
  • If you are moving yourself, use your inventory list to determine how many boxes you will need. Stock up on the items you’ll need from our “Moving Essentials” list.
  • Submit a change of address request through the USPS and update your address with banks, employers, insurance providers, subscription services, and other important accounts.
  • If you believe your move may qualify for tax-related benefits or deductions, consult a qualified tax professional.
  • If you’re moving to a new community, contact the Chamber of Commerce and school district and request information about services.
  • Make reservations with airlines, hotels, and car rental agencies, if needed.
  • Begin packing nonessential items.

Two to Four Weeks Before:

  • Arrange for storage, if needed.
  • If you have items you don’t want to pack and move, hold a yard sale.
  • Update the address listed on your car registration, license, and insurance.
  • Transfer your bank accounts and safe-deposit box items to new branch locations if needed. Cancel or redirect any direct deposit or automatic payments from your accounts.
  • Make special arrangements to move your pets, including updating identification tags and microchip information, gathering veterinary records, and creating a travel plan that keeps them comfortable throughout the move.
  • Have your car checked and serviced if you’ll need to drive it a long distance.
  • Change your utilities, including phone, power, and water, from your old address to your new address.

Digital Moving Checklist:

  • Transfer internet and streaming services.
  • Update your address for online shopping accounts and subscriptions.
  • Update banking, insurance, and employer records.
  • Back up important digital files and documents before your move.

Week of Moving Day:

  • Defrost your refrigerator and freezer.
  • Have movers pack your belongings.
  • Label each box with the contents and the room where you want it to be delivered.
  • If you’re using a moving company, arrange to pay for their services in full, or the remainder of what you owe, upon delivery.
  • Set aside legal documents and valuables that you do not want packed.
  • Pack clothing and toiletries, along with extra clothes in case the moving company is delayed.
  • Give your travel itinerary to a close friend or relative so they can reach you as needed.
  • Pack a first-day box with items that you’ll want accessible before other boxes are unpacked. See our list of suggested items on the right and add any others you’ll want to include.

Moving Day: 

Old Home

  • Pick up the truck as early as possible if you are moving yourself.
  • Make a list of every item and box loaded on the truck.
  • Let the mover know how to reach you.
  • Double-check your closets, cupboards, attic, basement, yard, and garage for any left-behind items.

New Home

  • Be on hand at the new home to answer questions and give instructions to the mover.
  • Check off boxes and items as they come off the truck.
  • Install new locks.
  • Confirm that the utilities have been turned on and are ready for use.
  • Unpack your first-day box.
  • Unpack your children’s toys and find a safe place for them to play.
  • Examine your goods for damage.

FAQs About Moving: 

When Should I Start Preparing for a Move?

Most moving professionals recommend beginning preparations at least six to eight weeks before moving day.

Should I Hire Movers or Move Myself?

The right choice depends on your budget, timeline, distance, and the amount of belongings you need to transport.

What Should I Pack in a First-Day Box?

Include toiletries, medications, chargers, important documents, snacks, basic cleaning supplies, and a change of clothes.

When Should I Transfer Utilities?

Most utility transfers should be scheduled two to four weeks before moving day to help avoid service interruptions.

Our Moving Checklist page has all the information above, plus helpful lists for Moving Essentials and which items to pack in your First-Day Box available as a downloadable PDF.

For additional information on the selling process from start to finish, tips on working with an agent, and more, visit Windermere’s Home Selling Guide:

Living • June 4, 2026

Home Maintenance Checklist: Summer Edition

As summer nears, who doesn’t dream of camping trips, weekend getaways, and hammock lay-arounds? But before you book your entire summer, remember that it’s also an important time for home maintenance and repair, particularly outdoors. Whether you’re prepping your home for summer fun or enhancing its efficiency, here’s a checklist to consider while the weather is warm.

Check and service AC system

Optimize your home for cooler temperatures by having your AC system checked and serviced, which prolongs the life of your unit and prevents costly repairs. Also be sure to change the AC filter regularly — up to once a month in the summer.

Seal air escape routes

Keep cool air from escaping by sealing your windows and doors tight. Check for any gaps or cracks in your window seals and door frames. Replace weatherstripping or apply caulking as needed to improve energy efficiency and keep costs down.

Maintain your patios and fencing

Spruce up your deck, patio, and fence by sweeping away debris, cleaning and sealing surfaces, and checking for needed repairs. Mold and mildew are common here, so consider pressure washing on a lower setting before sealing to keep everything looking fresh and clean.

Prep for summer entertaining

Give your grilling surfaces a makeover by removing built-up grease and debris from the grill grates, burners, and drip pans. Next, check your propane levels to ensure you’re ready for the season. Also wipe down your outdoor furniture and lighting and replace burnt-out bulbs, so guests have a comfortable, well-lit space to relax.

Inspect your roof

The warm, dry air makes summer the perfect time for roof maintenance. Look for damaged or missing shingles, soft spots, or areas where roof flashing may need repair. While you can handle some repairs yourself — flashing issues can often be fixed with a new layer of caulk or mortar — it’s best to hire a professional if you see signs of water damage.

Fix your gutters

Cleaning your gutters may be a year-round affair, but gutter repair is a warm-weather activity. Inspect your gutters and downspouts for cracks, sags, loose fasteners, and rust spots and fix as necessary. You can seal smaller leaks with gutter sealant or a patch kit, but you’ll likely want to replace sections with more significant damage.

Give your garden some love

Weeds can flourish in hot weather and compete with your plants for moisture and nutrients. Combat this by regularly pulling weeds and applying a 2-inch layer of mulch in your planting areas. Also, remember to water wisely, preferably early in the morning or late in the evening, to minimize evaporation and ensure efficient water usage.

Tend to your pool

Your pool has been waiting all year to show off. Keep it pristine and safe for swimmers by
regularly checking and maintaining the chemical levels to prevent contaminants and pollutants. Another safety tip: ensure all safety equipment, such as pool covers and ladders, are in good condition.

Most important of all, take advantage of the sunshine for some well-deserved R&R!

Real Estate News & Information • June 2, 2026

Mortgage Types 101: Understanding Your Home Loan Options

Buying a home comes with plenty of exciting milestones like touring properties, envisioning your future space, and making an offer. But before you get the keys, there’s one piece of the process that often feels the most intimidating: financing.

From fixed-rate loans and adjustable-rate mortgages to FHA and VA programs, today’s buyers have more financing options than ever before. Understanding the basics can help you feel more confident when it’s time to talk with a lender and determine what loan best aligns with your goals.

Whether you’re preparing to buy your first home or simply looking to refresh your knowledge, consider this your guide to mortgage basics.

What Is a Mortgage?

A mortgage is a loan used to purchase a home. Instead of paying the entire price of the property at once, homebuyers typically finance the purchase through a lender and make payments over time. Those payments typically principal and interest on the loan, property taxes, homeowners’ insurance, and, in some cases, mortgage insurance. The home serves as security for the loan until the borrower fully repays it.

Why Mortgage Choice Matters

Not all mortgages are created equal. The type of loan you choose can affect everything from your monthly payment and interest rate to your required down payment and long-term borrowing costs. Some loan programs may offer lower upfront costs, while others provide greater payment stability or flexibility down the road. That’s why working with both a trusted lender and a knowledgeable real estate professional can help ensure that you’re evaluating options that fit your financial picture—not just today, but years down the road.

Fixed-Rate vs. Adjustable-Rate Mortgages

One of the first decisions many buyers face is whether they prefer a fixed or adjustable interest rate. Let’s break them down.

Fixed-Rate Mortgage

Fixed-rate mortgages offer long-term consistency because the interest rate stays locked in for the duration of the loan, resulting in more stable monthly payments. This predictability makes fixed-rate loans especially appealing for buyers who plan to stay in their home for many years or simply prefer the peace of mind that comes with stable monthly housing costs. While fixed-rate mortgages can carry slightly higher initial rates than some adjustable-rate options, they offer protection against future rate increases and make long-term budgeting much easier.

Adjustable-Rate Mortgage (ARM)

An adjustable-rate mortgage starts with a fixed interest rate for a set period, then transitions to a variable rate that can change with market conditions. You may see ARMs described as 5/1, 7/1, or 10/1 loans, with the first number representing the length of the introductory fixed-rate period and the second indicating how often the rate can adjust afterward. Because ARMs often begin with lower interest rates than fixed-rate mortgages, they can provide lower initial monthly payments. However, buyers should be aware that payments may increase if interest rates rise. For homeowners who anticipate moving, selling, or refinancing before the adjustment period begins, an ARM may be worth considering.

Understanding the Most Common Loan Programs

Beyond choosing between a fixed-rate and an adjustable-rate mortgage, buyers can select from several loan programs based on their financial situation, credit history, and homeownership goals. While a lender can help determine which option is best for you, understanding the basics can make conversations about financing feel much less overwhelming.

Conventional Loans

Conventional loans are one of the most common mortgage options and are typically provided by private lenders, including banks, credit unions, and mortgage companies. They are often a strong choice for buyers with solid credit, stable income, and funds available for a down payment. While some conventional loan programs allow down payments below 20%, borrowers may be required to pay private mortgage insurance (PMI) until they build enough equity in the home.

FHA Loans

Backed by the Federal Housing Administration, FHA loans help make homeownership more accessible for qualified buyers. Because they offer lower down payment options and more flexible credit requirements, these loans are a popular choice among many first-time homebuyers. Borrowers should keep in mind that mortgage insurance is typically required for the loan.

VA Loans

VA loans are available to eligible military service members, veterans, and certain surviving spouses. One of the program’s biggest advantages is that qualified borrowers can purchase a home with no down payment. VA loans also typically offer competitive interest rates and do not require private mortgage insurance.

USDA Loans

USDA loans are intended for eligible buyers purchasing homes in designated rural and suburban communities. Qualified borrowers may be able to purchase a home with no down payment and favorable financing terms, though income and location requirements apply.

Jumbo Loans

Jumbo loans are used when a home’s purchase price exceeds the loan limits established for conventional mortgages. These loans are often common in higher-cost real estate markets and may require stronger credit qualifications, larger down payments, and additional financial documentation during the approval process.

Choosing a Loan Term

In addition to selecting a loan type, buyers will also choose a loan term. The most common options are 15-year and 30-year mortgages. A 30-year mortgage often comes with lower monthly payments because the loan is repaid over a longer period, while a 15-year mortgage can offer lower interest rates and help homeowners build equity more quickly. Although monthly payments on a shorter-term loan are often higher, borrowers typically pay significantly less interest over the life of the loan.

Which Mortgage Is Right for You?

The best mortgage isn’t necessarily the one with the lowest rate—it’s the one that aligns with your budget, financial goals, and long-term plans. Factors such as your down payment, credit profile, anticipated homeownership lenght, and monthly budget can all influence which loan type makes the most sense. A trusted lender can help you compare options and understand how each program may impact your monthly payment and overall cost of homeownership.

How Much House Can You Afford?

While online calculators can provide a starting point, affordability involves more than a monthly mortgage payment. Buyers should consider existing debt obligations, emergency savings goals, everyday living expenses, future financial plans, property taxes, insurance costs, and ongoing home maintenance. Understanding the full picture can help ensure your home purchase supports your lifestyle rather than stretching your budget too thin.

Mortgage Terms Every Buyer Should Know

Conversations about financing can feel like a completely different language. Here’s a quick cheat sheet for some of the most common mortgage terms:

Amortization

The process of gradually paying off a loan through scheduled payments over time.

APR (Annual Percentage Rate)

A broader measure of borrowing cost that includes interest and certain lender fees.

Closing Costs

Expenses associated with finalizing a home purchase, often include lender fees, title services, escrow fees, and other transaction-related costs.

Down Payment

The portion of a home’s purchase price paid by the buyer upfront.

Escrow

An account used to hold funds for property taxes, homeowners’ insurance, and other transaction-related expenses.

Mortgage Insurance

Insurance that protects the lender if a borrower defaults on the loan. It may be required for certain loan types or lower down payment programs.

Preapproval

A lender’s preliminary review of your finances that estimates how much you may qualify to borrow.

Principal

The original amount borrowed before interest is applied.

The Bottom Line

Choosing a mortgage isn’t about finding a universally “best” loan—it’s about finding the option that best supports your financial goals, timeline, and homeownership plans.